Publications
Ankara’s Southern Flank: Turkish Defence Diplomacy in South America, and the Argentine Exception
Dr Daniel Amicci Mussati
Analysis Series
Analysis/0068/August/2026/London-Dialogue. 23 August 2026
Author: Dr. Daniel Amicci Mussati
Overview
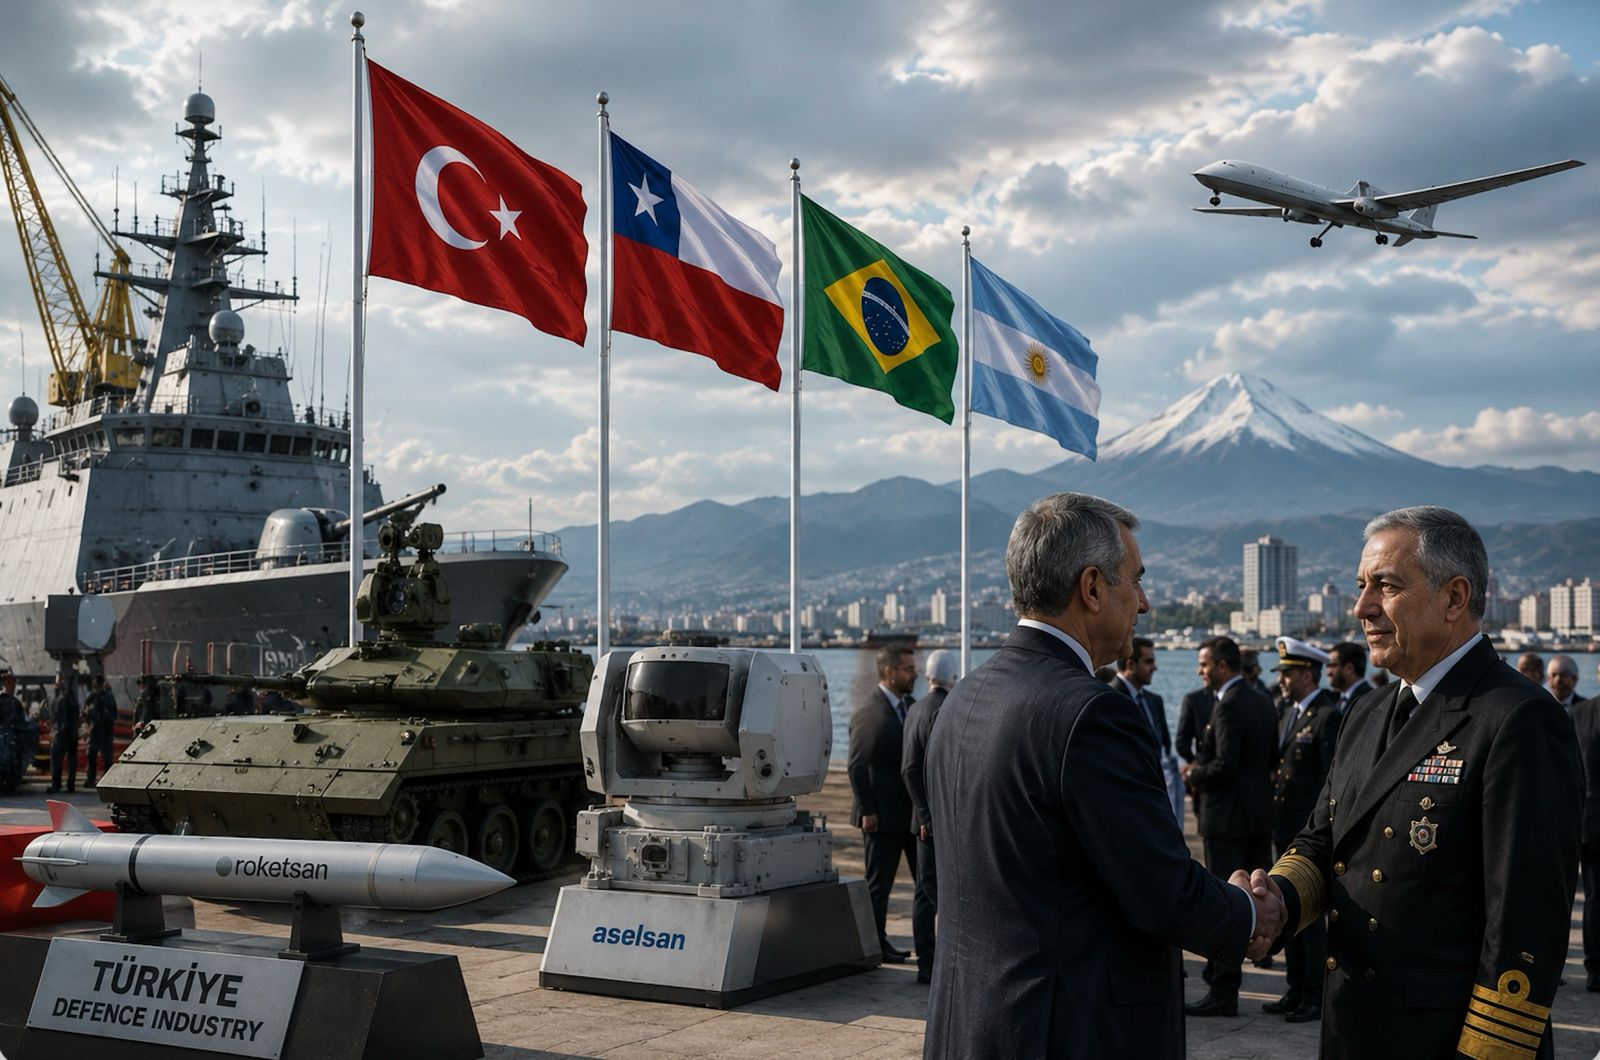
Over the past three years, Turkey’s defence industry has quietly established itself as a credible non-Western supplier across South America’s three largest markets for military modernisation: Chile, Brazil, and Argentina. The pattern is consistent with Ankara’s broader export strategy, bilateral agreements built around technology transfer rather than simple platform sales, and it has already produced concrete naval, land and aerospace deals in Santiago and Brasília. Buenos Aires is the exception. An Argentine naval modernisation package on offer from ASELSAN since December 2023 remains unsigned nearly three years on, even as the same company has closed comparable deals with Argentina’s neighbours in the interim. Budgetary constraint is the official explanation, but it does not obviously account for why the same fiscal and bureaucratic pressures faced by Chile and Brazil have not produced the same outcome. This brief sets out the evidence for Turkey’s regional expansion, examines the Argentine case in detail, and offers a cautious, clearly flagged hypothesis for the anomaly.
Chile: The Validation Case
Chile has emerged as the clearest proof of concept for Turkey’s regional strategy, with agreements now spanning all three of its principal defence-industrial branches. In the naval domain, HAVELSAN signed an agreement with the Chilean Navy in March 2025 to integrate its ADVENT combat management system into two M-class (Karel Doorman) frigates, the Almirante Blanco Encalada and the Almirante Riveros. The four-year integration project made Chile the ninth country worldwide — and the first in South America — to adopt the ADVENT system, a platform that HAVELSAN developed for the Turkish Navy and has since exported to multiple fleets.
On land, ASELSAN was awarded a contract in July 2023, in partnership with Chile’s state arsenal FAMAE, to modernise the fire-control systems of the Chilean Army’s Leopard 2A4 fleet, as well as the internal communications systems of the Leopard, Marder 1A3, and M109 platforms. The agreement notably included a technology-transfer component intended to expand FAMAE’s own industrial capacity, rather than a straightforward sale of Turkish equipment. The first modernised tanks were delivered in 2025, and the programme has since moved into serial integration.
Most recently, in April 2026, the state aerospace firm ENAER signed a cooperation agreement with Turkish Aerospace Industries (TAI) covering unmanned aerial systems, with subsequent reporting indicating the collaboration is oriented towards a Chilean UAV project based on TAI’s existing Anka or Aksungur platforms. Taken together, the three agreements place Turkey simultaneously inside Chile’s naval, land and aerospace state-defence enterprises — an unusually broad foothold for a supplier that, a decade ago, had little presence in the Southern Cone.
Brazil: Deepening Industrial Integration
Brazil’s engagement with Turkish suppliers has followed a similar logic, albeit through a single but symbolically significant deal. At the LAAD Defence and Security fair in April 2025, Kale Jet Engines signed a contract with the Brazilian firm SIATT to supply KTJ-3200 turbojet engines for the MANSUP-ER anti-ship missile — the extended-range variant of Brazil’s indigenous MANSUP system, intended to arm the new Tamandaré-class frigates. The agreement marked Turkey’s first-ever export of a jet engine for a missile system, and Turkish officials publicly framed it as a milestone in the country’s defence-industrial trajectory. It is worth noting, for the sake of precision, that SIATT is majority-Brazilian but was partly acquired (50 per cent) by the UAE-based EDGE Group in 2023, meaning the Turkish-Brazilian relationship sits within a wider, multi-party industrial arrangement rather than a purely bilateral one. Even accounting for that nuance, the deal illustrates the same pattern seen in Chile: Turkish suppliers entering via a specific technical niche, propulsion, fire control, or combat management, rather than attempting to displace an established prime contractor outright.
Argentina: The Stalled Offer
Argentina presents a marked contrast. ASELSAN first put forward a proposal to modernise the Argentine Navy’s three MEKO 360 (Almirante Brown-class) destroyers in December 2023, drawing on its experience upgrading the Turkish Navy’s own Barbaros-class (MEKO 200TN) frigates. The offer was refined and formally presented at LAAD 2025, where ASELSAN’s chief executive, Ahmet Akyol, outlined a package comprising long-range radar, ISR systems, sonar, electronic warfare suites, and a modernised combat management system. Nearly three years after the initial approach, the proposal remains under evaluation, with no contract signed.
The Argentine Navy has been explicit that MEKO 360 modernisation sits behind two other priorities — new submarines and the acquisition of two multipurpose frigates — in its capital planning, and it continues to weigh European alternatives to the Turkish package, principally Denmark’s Iver Huitfeldt class, Norway’s Fridtjof Nansen class, and Italy’s now-retired Maestrale class. Budgetary constraint is the consistent official explanation for the delay, and it is a genuine one: Argentina’s broader defence modernisation programme, including its F-16 acquisition, has been repeatedly described by its own armed forces as contingent on financing that has yet to be fully secured.
What is less easily explained is why an identical set of pressures, tight budgets, competing procurement priorities, and slow-moving bureaucracies have not produced comparable stagnation in Santiago or Brasília, where ASELSAN and its Turkish peers have converted proposals into signed contracts within roughly eighteen months to two years. This is not, in itself, evidence of anything beyond ordinary variation in procurement cycles. But in a dossier where the standard explanatory variables are held broadly constant across three cases, and the outcome diverges sharply in one, the divergence merits closer attention than it has so far received.
A Hypothesis, Clearly Flagged as Such
One variable that is rarely mentioned in coverage of the Argentine case, and for which there is no confirmed causal evidence, concerns the informal influence attributed, by some sources, though disputed by others, to Eduardo Eurnekian, the Argentine-Armenian businessman for whose holding company Javier Milei worked for over a decade prior to his entry into politics. Argentina formally recognised the Armenian genocide in December 2006, is home to the region’s largest Armenian community, and unlike Chile or Brazil — carries no equivalent domestic constituency invested in the bilateral relationship with Turkey. Armenia and Turkey, for their part, have no formal diplomatic relations. Whether any of this bears on the MEKO 360 decision is, to be clear, unverified and speculative; procurement decisions of this kind are also shaped by financing terms, technical risk assessments, and competing offers on their own merits, any of which could fully account for the delay without reference to Eurnekian at all. The point is not to assert a causal link but to note that the standard explanation, budget alone, sits uneasily alongside the comparative evidence from Argentina’s neighbours and that this is one plausible additional layer among several worth setting out rather than ignoring.
Strategic Implications
For an institutional audience following European and Atlantic defence-industrial competition, the South American case is a useful microcosm of Turkey’s wider export strategy: enter through a specific technical capability, embed via technology transfer, and use early wins as reference cases for subsequent bids, the same approach that has underpinned Ankara’s expansion into European and Gulf markets, and one that increasingly positions Turkey as a genuine alternative to traditional Western and Russian suppliers in markets historically dominated by them. Chile validates the model; Brazil deepens it. Argentina, for reasons that remain only partly explained, is the open case in an otherwise coherent regional story and one worth revisiting, as the MEKO 360 decision, whenever it comes, is likely to say as much about Buenos Aires’s internal political dynamics as about naval procurement itself.
Dr Daniel Amicci Mussati
Related posts
The Maritime Blockade and the Strategic Calculus of the U.S., Iran, and Israel Toward a Renewed Armed Confrontation
Understanding Asim Munir’s Doctrine: Regime Security in Place of a National Goal
The Data Dilemma: Navigating the AI Systems Matrix
The Anatomy of a Shortfall: Europe’s Nine Capability Areas and the Lessons for Pakistan
From Quiet Diplomacy to Attempted Maritime Security Governance: Oman’s Role and Limits in the 2026 Strait of Hormuz Crisis
Anatomy of Asymmetry: How a Weaker State Converts Vulnerability into Leverage
Integration for Stability: The SDF’s Dissolution and Syria’s Security Order
The Western Flank Unravelled: Cross-Border Militancy, TTP Resurgence, and Afghan Taliban Governance
The Time of Guards Tank Divisions is Gone, or Maybe It is Not?
Re-pricing Israel’s Corridor: The Mecca Alliance and IMEC
The SCO at 25: From Regional Security Mechanism to Platform for a Multipolar Eurasia
Imran Khan: The Last Hope of a Nation
London Dialogue — Founding Statement
Publication Categories
- Analysis (85)
- Book Review (1)
- Commentary (4)
- Essay (7)
- Journal (0)
- Journal Article (0)
- Policy Brief (5)
- Research Article (2)
- Research Report (3)
- Working Paper (0)
- Young Writers Corner (0)